
The PMJJBY Guide 2026 explains who is eligible for the Pradhan Mantri Jeevan Jyoti Bima Yojana, how to enrol, and how its ₹2 lakh life insurance cover works. If you are checking the PMJJBY eligibility criteria, age limit, annual premium or claim rules, this guide will help you understand the scheme in simple language.
Life insurance can help a family manage some of the financial pressure that follows the death of an earning member. But many families delay buying cover because they believe insurance is always expensive.
The Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) offers a simple, bank-linked life insurance option. It provides ₹2 lakh of life cover for death due to any cause, subject to the scheme’s terms and conditions. The official annual premium is ₹436.
This guide explains who can join, how the premium is paid, how to enrol, and what a nominee should do when making a claim.
What is PMJJBY?
PMJJBY is a one-year renewable term life insurance scheme offered through participating banks and post offices in partnership with authorised life insurers.
It is designed to provide basic life cover at a relatively low annual cost. It is not a savings or investment plan: it does not provide a maturity payment simply because the policyholder survives the year.
PMJJBY Guide 2026: Key Scheme Details
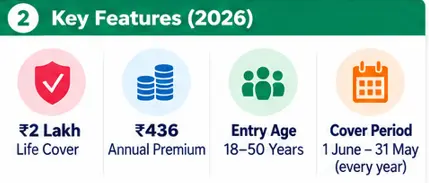
| Feature | Official scheme detail |
|---|---|
| Life cover | ₹2 lakh |
| Annual premium | ₹436 |
| Eligible entry age | 18–50 years |
| Cover period | 1 June to 31 May |
| Premium payment | Auto-debit from the linked eligible bank or post office account |
| Benefit recipient | Nominee or eligible claimant, according to the claim rules |
| Nature of cover | One-year renewable term life insurance |
The premium may be collected on a pro-rata basis for eligible first-time enrolments made during the policy year. Check the amount payable with your participating bank or post office before enrolling.
Important: The ₹2 lakh benefit is payable on the insured person’s death, subject to the policy conditions. PMJJBY does not pay ₹2 lakh every year, and it does not offer a maturity benefit.
Who is eligible for PMJJBY?
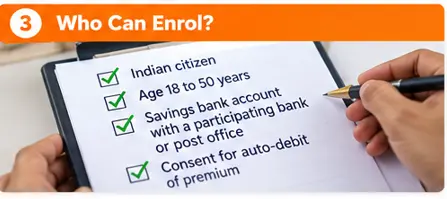
You may be eligible if you:
- Are within the permitted entry age of 18–50 years.
- Hold an eligible individual savings account with a participating bank or post office.
- Give the required consent for enrolment and premium auto-debit.
- Meet the scheme’s enrolment and documentation requirements.
A person with accounts at multiple banks cannot obtain multiple full PMJJBY benefits. The scheme limits cover to ₹2 lakh, and it may forfeit duplicate premiums.
This PMJJBY Guide also explains why meeting the age requirement alone is not enough; eligible account details, enrolment consent and premium payment matter too.
How to enrol in PMJJBY
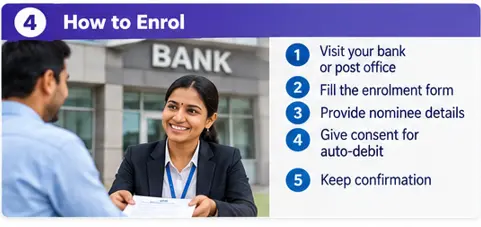
- Contact the bank branch or post office where you hold an eligible account, or check whether it offers online enrolment.
- Request the PMJJBY enrolment form or use the official digital process offered by your institution.
- Provide the required personal, account, nominee and declaration details.
- Give consent for the annual premium to be deducted automatically.
- Keep the acknowledgement or confirmation and check that the cover is active.
Do not assume that simply holding a bank account means you are enrolled. Confirm enrolment and successful premium deduction with your bank or post office.
Important waiting-period rule
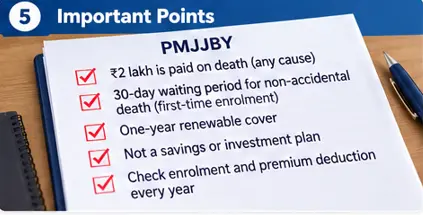
For a person enrolling for the first time, the official scheme states that death due to a cause other than an accident is not covered during the first 30 days after enrolment. Accidental death is treated differently under this rule.
Read the scheme’s current terms and ask the participating institution if you are unsure when your cover begins.
PMJJBY claim process: What should the nominee do?
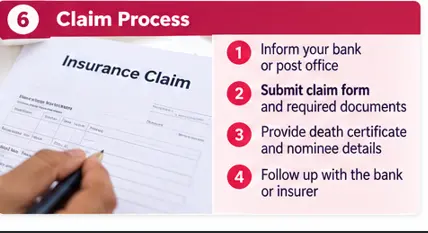
If the insured person dies, the nominee or claimant should contact the bank or post office linked to the policy as soon as possible.
The usual process is:
- Inform the linked institution. Tell the bank or post office that the insured person has died and that you want to submit a PMJJBY claim.
- Obtain the current claim form. Use the form and instructions provided by the bank or insurer.
- Submit the required records. These may include the death certificate, claimant and nominee identity or bank details, and other documents requested under the applicable claim process.
- Provide additional evidence if requested. The insurer may need further information depending on the circumstances of death.
- Keep the acknowledgement. Record the submission date and reference number, and follow up through the bank or insurer.
The exact documents and procedure can vary with the claim circumstances. Use the current form from the participating bank or insurer rather than relying on an old downloaded checklist.
Why can a PMJJBY claim be delayed?
Possible reasons include incomplete documents, mismatched nominee details, missing enrolment records, an unresolved premium deduction, or questions about the policy’s coverage period.
The nominee should ask the bank or insurer which requirement remains outstanding and request written clarification where possible. Keep copies of submitted documents and all communications.
Use this PMJJBY Guide as a starting point, and confirm the latest scheme conditions with the official Department of Financial Services website or your participating bank.
Final takeaway
PMJJBY offers ₹2 lakh of basic life cover at an official annual premium of ₹436. It may help eligible families access a modest level of financial protection, but it should not automatically be treated as a replacement for a larger life insurance plan where the family’s needs require more cover.
Before enrolling, verify your eligibility, premium deduction, nominee details, and policy status. If a claim arises, contact the linked bank or post office promptly and follow the current insurer’s instructions.
Frequently asked questions
Q1. Is PMJJBY available to people over 50?
The permitted entry age is 18–50 years. If you enrolled earlier, ask your bank or insurer about the applicable continuation and renewal rules; do not assume that new enrolment is available after the entry-age limit.
Q2. Does PMJJBY cover natural death?
Yes. PMJJBY provides life cover for death due to any cause, subject to its terms, including the first-30-day restriction for non-accidental death after first-time enrolment.
Q3. Does PMJJBY pay money at maturity?
No. It is a term life insurance scheme, not an investment or savings product. There is no maturity benefit for surviving the cover period.
Q4. Where can I check the official rules?
Visit the Department of Financial Services PMJJBY page and confirm enrolment or claim requirements with your participating bank or post office.
Related Guide
1. PMJJBY Eligibility 2026: Who Can Get ₹2 Lakh Life Cover?
2. PMJJBY Premium 2026: ₹436 Annual Premium and Auto-Debit Rules
3. How to Apply for PMJJBY Online and Through Your Bank in 2026
4. PMJJBY Claim Process 2026: Documents, Forms and How to Claim ₹2 Lakh
5. PMJJBY Claim Rejected or Delayed? Reasons and What to Do
6. PMJJBY vs PMSBY 2026: Difference Between Life and Accident Insurance