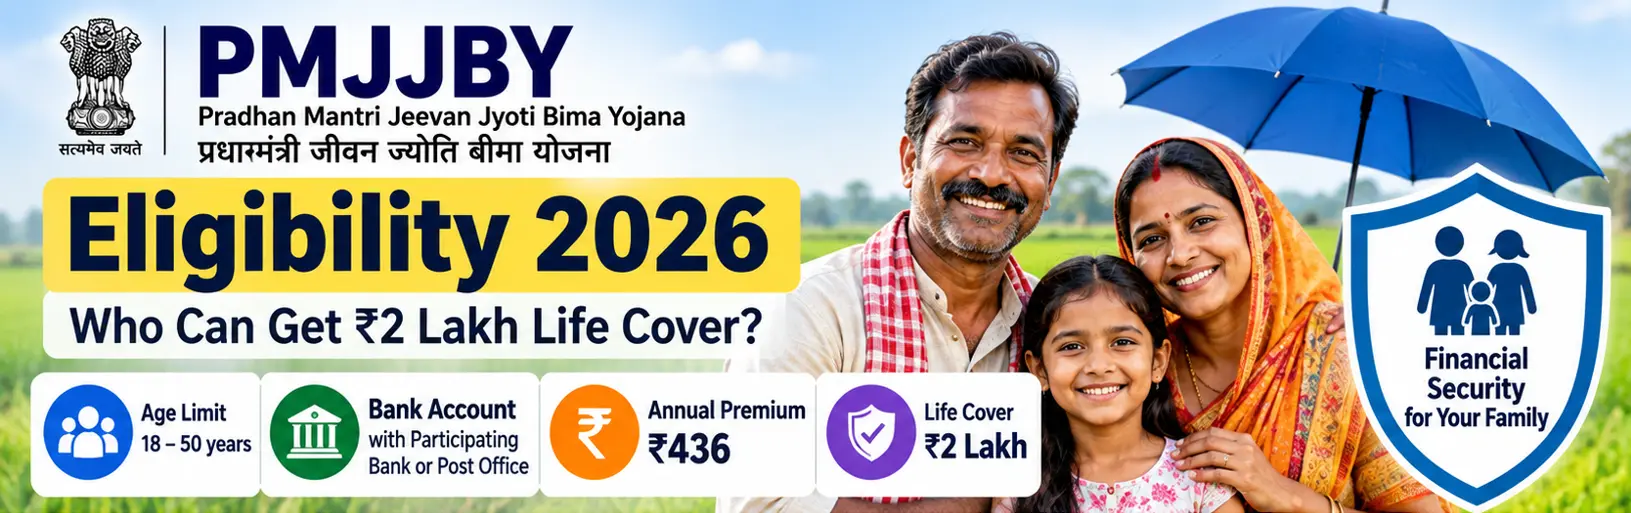
PMJJBY eligibility is one of the first things to check before enrolling in the Pradhan Mantri Jeevan Jyoti Bima Yojana. The scheme provides ₹2 lakh of life insurance cover for a relatively low annual premium.
However, having a bank account alone does not automatically mean that you are covered. You must meet the age requirement, enrol through a participating bank or post office, provide the required consent and ensure that your insurance remains active.
In this guide, we explain who can join PMJJBY in 2026, what the scheme covers, how to enrol and which rules you should check before depending on this insurance.
What Is PMJJBY?
The Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) is a government-backed, one-year renewable term life insurance scheme administered through participating banks and post offices in partnership with authorised life insurers.
Its main purpose is to make basic life insurance more accessible to eligible people.
Here are the key details:
| Feature | Details |
|---|---|
| Insurance cover | ₹2 lakh |
| Annual premium | ₹436, according to the current official scheme information |
| Eligible entry age | 18–50 years |
| Type of insurance | Term life insurance |
| Cover period | 1 June to 31 May |
| Premium payment | Auto-debit from the designated bank or post-office account |
| Benefit payable | Nominee or eligible beneficiary following the insured person’s death, subject to scheme rules |
| Maturity benefit | No |
| Renewal | Yearly, subject to scheme conditions |
The official scheme information is available on the Department of Financial Services website.
Who Is Eligible for PMJJBY in 2026?
You can generally enrol in PMJJBY if you meet the following conditions.
1. You must be between 18 and 50 years old when joining
The scheme is open to eligible individuals aged 18–50 years.
You cannot make a first-time entry after the age of 50 under the standard entry rules. However, someone who joined earlier may continue renewing the cover until the scheme’s specified termination age, subject to the conditions.
The official scheme rules provide for termination of life cover at age 55, subject to annual renewal up to that date.
Example: If you are 35 years old and have an eligible bank account, you meet the basic age condition. You must still complete enrolment and satisfy the other requirements.
2. You must have an eligible bank or post office account
You need an individual account with a participating bank or post office.
The account is used to collect the insurance premium through auto-debit. Institutional accounts are not eligible.
A savings account is commonly used, but you should confirm with your bank or post office that your particular account is eligible for PMJJBY enrolment.
3. You must give consent for enrolment and auto-debit
PMJJBY is not automatically active simply because you have a bank account.
You must opt in using the prescribed enrolment or consent process and authorise the premium deduction.
Keep the enrolment acknowledgement or confirmation message, if provided. It can help you verify whether your request was completed.
4. You must maintain sufficient funds for the premium
The annual premium is currently ₹436. The amount is collected from your designated account through auto-debit.
Keep enough money in the account when the premium is due. If the premium cannot be collected and the insurance lapses, you should not assume that your cover is still active.
Check with your bank if you are unsure whether the latest renewal has been completed.
Who Cannot Join PMJJBY?
You generally cannot enrol if:
- You are below 18 years of age.
- You are older than 50 and are trying to join for the first time.
- You do not have an eligible account with a participating bank or post office.
- You do not complete the required enrolment and consent process.
There is also an important rule about multiple accounts: one person can obtain PMJJBY cover through only one eligible account, even if they maintain accounts with several banks or post offices.
If premiums are collected through multiple accounts by mistake, the insurance cover is restricted to ₹2 lakh, and premiums paid for duplicate coverage may be forfeited.
Can Joint Bank Account Holders Join PMJJBY?
Yes. Eligible individual holders of a joint bank account can each enrol, provided each person independently meets the eligibility conditions and pays the applicable premium.
For example, a husband and wife who both meet the age requirement may each join through an eligible joint account, subject to the bank’s enrolment process.
Each person should complete the required consent and confirm their own enrolment. Do not assume that enrolling one account holder automatically covers the other.
What Does PMJJBY Cover?
PMJJBY provides ₹2 lakh of life insurance cover if the insured subscriber dies, subject to the scheme’s conditions.
The scheme covers death due to any cause, including natural causes and accidents. However, first-time enrolment and rejoining are subject to an important 30-day waiting-period rule.
Important: The 30-day waiting period
For a first-time enrolment or rejoining, death from a cause other than an accident during the first 30 days after enrolment is not covered under the scheme’s specified waiting-period rule.
Accidental death is treated differently under this rule.
Read the official terms carefully and confirm the start date of your cover. Do not assume that every type of death is covered immediately after making the first premium payment.
Does PMJJBY provide a maturity amount?
No. PMJJBY is a term life insurance scheme, not a savings or investment plan.
If the policyholder survives the coverage period, there is no maturity amount or surrender value payable under the scheme.
The purpose is to provide life cover, not to build an investment corpus.
How to Apply for PMJJBY
If you meet the PMJJBY eligibility conditions, follow these steps.
- Contact your bank or post office. Confirm that it participates in PMJJBY.
- Request the enrolment process. Ask for the prescribed form or check whether digital enrolment is available through your bank.
- Provide the required information. Complete the enrolment and consent details requested by the institution.
- Provide nominee details. Enter accurate nominee information and check the spelling and relationship details.
- Authorise auto-debit. Give consent for the applicable premium to be collected from your designated account.
- Keep the confirmation. Save the acknowledgement, SMS, email or other confirmation available from the bank.
- Check renewal each year. Make sure the premium has been collected and the cover remains active.
The official scheme page explains the enrolment rules and premium arrangements: PMJJBY — Department of Financial Services.
Documents and Details You May Need
The exact process can vary by participating institution. Before applying, ask your bank or post office what it requires.
Keep the following information readily available:
- Bank or post-office account details.
- Identity and personal details requested for enrolment.
- Mobile number and contact information.
- Nominee’s name and other required nominee details.
- Completed enrolment form or digital consent.
- Authorisation for premium auto-debit.
Do not share your banking PIN, OTP or password with anyone claiming to enrol you in the scheme.
Important PMJJBY Rules to Remember
Before joining, keep these points in mind:
- Annual renewal matters: PMJJBY provides one-year cover, generally from 1 June to 31 May.
- The premium may change: ₹436 is the current premium stated in the official scheme information; verify the applicable amount when enrolling or renewing.
- Cover ends under specified conditions: These include reaching the scheme’s termination age, closure of the designated account or insufficient balance affecting continuation of cover.
- Multiple accounts do not provide multiple payouts: The cover is restricted to ₹2 lakh per person under the scheme rules.
- Nominee information is important: Keep it accurate and updated through the prescribed process.
- Existing insurance can continue alongside PMJJBY: The scheme’s official FAQ states that PMJJBY cover can be in addition to other insurance coverage.
Final Takeaway
PMJJBY can provide a basic layer of financial protection for eligible families at a relatively low annual premium. To qualify, you must meet the age requirement, use an eligible bank or post-office account, complete enrolment and keep the cover active.
Before relying on the scheme, confirm your enrolment status, understand the 30-day waiting-period rule for non-accidental deaths after first-time enrolment or rejoining, and ensure your nominee details are correct.
Remember that ₹2 lakh may not be enough to replace a family’s full income or cover all its long-term financial needs. Consider PMJJBY as one part of your family’s financial protection, rather than a complete substitute for suitable life insurance.
Benefitomics — Discover. Understand. Benefit.
Frequently Asked Questions
1. What is the age limit for PMJJBY in 2026?
The entry age is 18–50 years. Eligible subscribers who joined earlier may continue renewing their cover until the scheme’s specified termination age, subject to its rules.
2. Can I join PMJJBY if I am 45 years old?
Yes, you can generally enrol if you are 45, have an eligible account with a participating institution and complete the required consent and premium process.
3. Can a person above 50 years renew PMJJBY?
The standard scheme rules allow eligible existing subscribers to renew up to the specified termination age of 55. First-time entry is not permitted beyond age 50.
4. Is PMJJBY automatically available to every bank account holder?
No. You must meet the eligibility conditions and complete the required enrolment and auto-debit consent process.
5. Can both husband and wife enrol in PMJJBY?
Yes. Each spouse can enrol separately if they meet the scheme’s conditions and complete the required process.
6. Can I enrol through two different bank accounts?
No. An individual can be covered through only one eligible account. Duplicate premiums do not create additional cover.
7. Is PMJJBY cover available immediately after enrolment?
For first-time enrolment or rejoining, a 30-day waiting period applies to death from causes other than an accident. Check the official terms for the precise conditions.
8. Will I get my premium back if I do not make a claim?
No. PMJJBY is term life insurance and does not provide a maturity or surrender benefit.
9. Can I have PMJJBY and a private life insurance policy together?
Yes. PMJJBY can be held in addition to other life insurance, subject to the terms of the respective policies.
10. Where can I check the official PMJJBY rules?
Visit the Department of Financial Services PMJJBY page or contact your participating bank or post office.
Related Posts
Main pillar: PMJJBY Guide 2026: ₹2 Lakh Life Insurance, Eligibility, Premium & Claim Process
PMJJBY Premium 2026: ₹436 Annual Premium and Auto-Debit Rules
How to Apply for PMJJBY Online and Through Your Bank in 2026
PMJJBY Claim Process 2026: Documents, Forms and How to Claim ₹2 Lakh
PMSBY Guide 2026: ₹2 Lakh Accident Cover, Eligibility, Premium & Claim Process