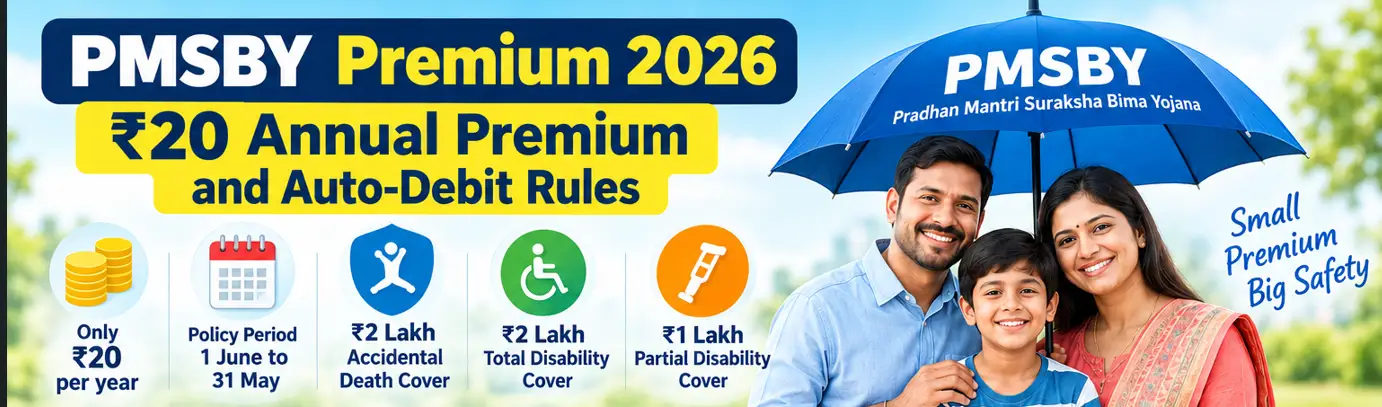
The PMSBY premium in 2026 is ₹20 per person per year. The Pradhan Mantri Suraksha Bima Yojana (PMSBY) is a government-backed personal accident insurance scheme for eligible people aged 18 to 70. The subscriber’s consent allows the premium to be deducted from a participating bank or post office account through auto-debit.
The low annual cost makes PMSBY accessible to many families. However, it is important to understand when the premium is deducted, how renewal works, and what happens if the account doesn’t have enough money.
This guide explains the PMSBY premium, payment rules, coverage period and steps you can take if your premium has not been deducted.
What is the PMSBY premium in 2026?
The current annual PMSBY premium is ₹20 per member.
| Detail | PMSBY rule |
|---|---|
| Annual premium | ₹20 per person |
| Payment method | Auto-debit from an eligible bank or post office account |
| Payment frequency | One annual instalment |
| Policy period | 1 June to 31 May |
| Accidental death benefit | ₹2 lakh |
| Specified permanent total disability benefit | ₹2 lakh |
| Specified permanent partial disability benefit | ₹1 lakh |
The premium and benefits above are stated on the official Department of Financial Services PMSBY page.
The premium is charged per enrolled person, not as one payment that automatically covers an entire family. Each eligible person must enrol separately and meet the scheme conditions.
1. How is the PMSBY premium paid?
PMSBY uses an auto-debit facility. When you enrol, you give consent for the participating bank or post office to deduct the annual premium from your designated account.
The process generally works as follows:
- You submit the PMSBY enrolment form or complete the available digital enrolment process.
- You authorise the annual premium deduction.
- Your participating institution processes the enrolment.
- The premium is deducted from your account.
- Your accident cover begins according to the scheme rules, including the applicable date of premium debit.
Keep your enrolment acknowledgement and any SMS or bank entry confirming the deduction. These records may be useful if you later need to verify your cover or make a claim.
You do not normally need to visit the branch every year if your auto-debit instruction remains active and renewal is processed successfully. However, check your account and scheme status rather than assuming that renewal has happened.
2. When is the PMSBY premium deducted?
The annual cover period runs from 1 June to 31 May.
For renewal, the scheme’s enrolment form authorises the bank or post office to deduct the premium around the annual renewal period. The exact processing date can depend on the institution’s procedures.
If you are already enrolled, check your account statement around the renewal period and confirm that the deduction was successful.
If you are joining for the first time or rejoining after leaving the scheme, you may be able to enrol later in the year by paying the annual premium. According to the official scheme rules, risk cover for such enrolment starts from the date the premium is auto-debited.
Do not assume that paying ₹20 at any point in the year automatically provides retrospective cover for an earlier accident.
3. What happens if your bank account does not have enough money?
Maintaining a sufficient balance is important because PMSBY premiums are collected through auto-debit.
If the account has insufficient funds when the premium is due, the deduction may fail. The scheme rules state that accident cover can terminate or be restricted when there is an insufficient balance to keep the insurance in force.
If you think your premium was missed, take these steps:
- Check your bank statement for the PMSBY debit.
- Contact your bank or post office to ask whether the renewal was processed.
- Confirm whether your enrolment remains active.
- Ask whether you need to complete a fresh enrolment or authorisation.
- Keep the bank’s response or confirmation for your records.
Do not assume that depositing money after a failed debit automatically restores cover. Ask the participating institution to confirm your status and the date from which cover applies.
4. Does the PMSBY premium increase with age?
The published PMSBY premium is ₹20 per person per year, subject to any official revision of the scheme’s terms. It is not presented as a premium that increases every year according to an individual’s age.
However, eligibility still matters. PMSBY is available to eligible people aged 18 to 70, and the cover terminates on reaching the scheme’s maximum age under its rules.
If you are approaching age 70, check your coverage status and the applicable termination conditions with your participating institution.
5. Do joint bank account holders each pay ₹20?
Yes. Eligible holders of a joint account may enrol separately if they satisfy the scheme’s conditions and authorise the premium deduction.
For example, if two eligible adults enrol through a joint account, the annual premium would be ₹20 per person, or ₹40 in total.
One person’s enrolment does not automatically insure every other holder of the account. Each member must meet the eligibility requirements and be enrolled correctly.
6. Can PMSBY deduct the premium from multiple bank accounts?
An individual can hold PMSBY cover through only one bank or post office account.
If you have accounts with two or more banks, choose one eligible account for enrolment and avoid duplicate enrolments. The official scheme rules state that if multiple premiums are received inadvertently, cover is restricted to one account and the additional premium may be liable to forfeiture.
Before enrolling through a new bank, check whether you already have PMSBY coverage through another account.
7. What insurance cover do you get for ₹20?
PMSBY is personal accident insurance. Its benefits depend on the outcome of a qualifying accident and the evidence submitted.
| Covered event under the scheme | Benefit |
|---|---|
| Accidental death | ₹2 lakh |
| Specified permanent total disability | ₹2 lakh |
| Specified permanent partial disability | ₹1 lakh |
The scheme’s definitions of permanent total and partial disability are specific. Not every injury or temporary disability qualifies.
PMSBY also does not reimburse hospitalisation expenses. It should not be treated as a replacement for health insurance or comprehensive life insurance.
For a detailed explanation of eligibility and benefits, read the complete PMSBY Guide 2026.
8. How can you check whether your PMSBY premium was deducted?
If you are unsure whether your premium was paid, follow these steps:
Step 1: Open your bank’s mobile app or internet banking service, if available.
Step 2: Check your account statement for the PMSBY premium deduction.
Step 3: If you cannot identify the transaction, contact your bank or post office and ask them to verify your PMSBY enrolment and premium status.
Step 4: Keep any confirmation or acknowledgement provided by the institution.
Step 5: If the premium was not deducted, ask what action is required to enrol or renew and when your cover would begin.
For official enrolment forms and scheme documents, visit the PMSBY forms page on Jan Suraksha.
Final takeaway
The PMSBY premium is currently ₹20 per person per year, paid through auto-debit from an eligible bank or post office account. The key is not just paying a small premium; it is making sure your enrolment is valid and your cover remains active.
Check your account around renewal time, keep your confirmation, and contact your bank or post office if a deduction fails.
Frequently asked questions about PMSBY premium
Q1. Is the PMSBY premium still ₹20 in 2026?
The Department of Financial Services currently lists the annual premium as ₹20 per member. Check the official scheme page for any future revision.
Q2. Is PMSBY premium paid monthly or yearly?
It is an annual premium, collected in one instalment through auto-debit with the subscriber’s consent.
Q3. Can I pay the PMSBY premium in cash at a bank branch?
The scheme is designed around enrolment and premium deduction from an eligible bank or post office account. Ask your participating institution about its available enrolment process rather than assuming cash payment is accepted as an alternative.
Q4. What happens if my PMSBY premium is not deducted?
Your renewal may not have been completed. Contact the bank or post office to confirm your status and ask what steps are needed. Do not assume that cover remains active after a failed deduction.
Q5. Can I join PMSBY in the middle of the year?
Eligible new entrants and people rejoining may enrol later, subject to scheme conditions and payment of the annual premium. Risk cover starts from the date the premium is auto-debited, according to the official rules.
Q6. Can my spouse and I both enrol in PMSBY?
Yes. If both meet the eligibility conditions, each can enrol and pay the applicable premium. A joint account does not automatically cover both people without separate enrolments.
Q7. Can I have PMSBY through two banks?
No. Cover is restricted to one account per person. Avoid duplicate enrolments.
Q8. Does the ₹20 premium cover hospital bills after an accident?
No. PMSBY does not reimburse hospitalisation expenses. Its benefits relate to accidental death and specified permanent disabilities under the scheme rules.
Related Posts
- PMSBY Guide (2026): ₹2 Lakh Accident Cover, Eligibility, Premium & Claim Process
- PMSBY Eligibility 2026: Who Can Get ₹2 Lakh Accident Cover?
- How to Apply for PMSBY Online in 2026: Step-by-Step Guide
- PMSBY Claim Process 2026: Documents Required and How to Claim
- PMSBY Claim Rejected or Delayed? Reasons and What to Do
- PMSBY Benefits 2026: Accidental Death, Disability Cover and Exclusions
Official sources
Benefitomics is an independent information website and is not an official government portal. Scheme rules and benefits are subject to official terms. Confirm your enrolment and coverage with your participating bank, post office or insurer.