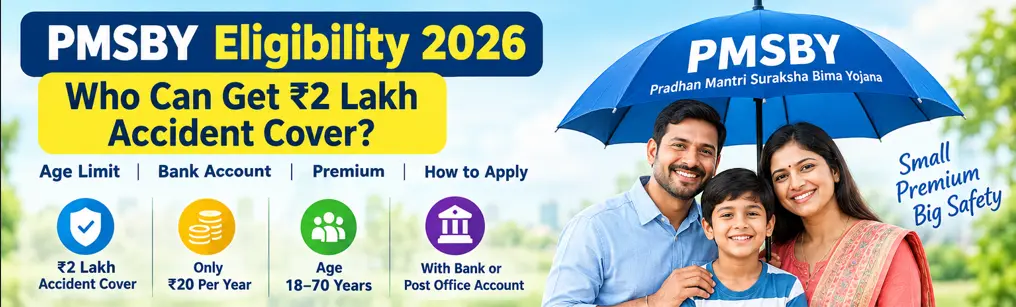
PMSBY eligibility in 2026: Indian residents and eligible non-resident Indians (NRIs) can enrol in the Pradhan Mantri Suraksha Bima Yojana (PMSBY) if they have an eligible bank or post office account, are aged 18 to 70 years, and consent to join the scheme with premium auto-debit. The annual premium is ₹20 per person, and the scheme provides up to ₹2 lakh for accidental death or specified permanent total disability, subject to its rules.
PMSBY is designed to make basic accident insurance affordable. However, having a bank account alone does not automatically provide coverage. You must enrol, authorise the premium deduction and ensure that your insurance cover is active.
This guide explains who can join PMSBY, the age limit, rules for joint and multiple accounts, and what to check before applying.
Who is eligible for PMSBY in 2026?
To qualify for the Pradhan Mantri Suraksha Bima Yojana, you generally need to meet these conditions:
- Age: You must be at least 18 and not have reached the scheme’s maximum age of 70, as determined under its age rules.
- Eligible account: You must have an eligible individual bank or post office account linked to the participating scheme.
- Consent: You must agree to enrol and authorise the annual premium deduction.
- Premium: The annual premium is currently ₹20 per person.
- Active cover: Your enrolment and premium payment must be for the risk cover to apply.
PMSBY is available through participating banks and post offices. The scheme is administered by approved general insurance companies in partnership with these institutions.
You can check the official rules on the Department of Financial Services PMSBY page.
PMSBY eligibility at a glance

| Eligibility detail | Rule |
|---|---|
| Minimum age | 18 years |
| Maximum age | 70 years, subject to the scheme’s age rules |
| Eligible account | Individual account with a participating bank or post office |
| Annual premium | ₹20 per person |
| Premium payment | Auto-debit with consent |
| Accidental death benefit | ₹2 lakh |
| Specified permanent total disability benefit | ₹2 lakh |
| Specified permanent partial disability benefit | ₹1 lakh |
| Coverage period | 1 June to 31 May, subject to enrolment and scheme conditions |
These are the scheme’s main rules. The amount payable depends on the nature of the accident and the disability or death established by the required evidence.
1. What is the minimum and maximum age for PMSBY?
The entry age for PMSBY is 18 to 70 years.
A person who has completed 18 years can apply if the other eligibility conditions are met. The scheme’s maximum age rule also matters: cover terminates on attaining age 70, as specified in the scheme rules.
For example, a 25-year-old or 55-year-old with an eligible account may enrol. A person who has reached the scheme’s maximum age cannot assume that they can start or continue cover.
If you are approaching age 70, check your current enrolment and coverage status with your bank or post office rather than relying only on an old SMS or deduction entry.
2. Is a bank account compulsory for PMSBY?
Yes. PMSBY is linked to an eligible bank or post office account with a participating institution.
You need to give consent for the annual premium to be deducted from the designated account. The current premium is ₹20 per member per year.
Before enrolling, check that:
- Your account is active.
- The bank or post office participates in PMSBY.
- You can authorise the premium deduction.
- You have provided the required enrolment details and nominee information.
An account opening by itself does not mean that you are insured. Confirm that your PMSBY enrolment has been completed and that the premium has been deducted.
3. Can joint bank account holders join PMSBY?
Yes. Each eligible holder of a joint account can enrol, provided each person meets the age and other eligibility conditions and pays the applicable premium.
For example, if two eligible adults hold a joint account, both may join PMSBY. At the current rate, the annual premium would be ₹20 per person, or ₹40 for both.
Each person’s enrolment and consent must be properly recorded. Do not assume that one person’s enrolment automatically covers every holder of the account.
4. Can I enrol in PMSBY through multiple bank accounts?
No. An individual can have PMSBY cover through only one bank or post office account, even if they maintain accounts at different institutions.
Suppose you have savings accounts with two banks. You should select one eligible account for PMSBY enrolment and authorise the premium deduction from that account.
If premiums are inadvertently collected through multiple accounts, the scheme does not provide multiple independent claims. Cover is restricted under the scheme rules, and an extra premium may be liable to forfeiture.
This is why it is important to check existing enrolment before joining again through another bank.
5. Are NRIs eligible for PMSBY?
Yes. An NRI may enrol if they have an eligible bank account with a bank branch located in India and satisfy the scheme’s conditions.
If a valid claim arises, the benefit is payable in Indian currency to the eligible beneficiary or nominee.
NRIs should confirm the account’s eligibility, enrolment process and documentation requirements with their participating bank before applying.
6. What benefits can an eligible PMSBY member receive?
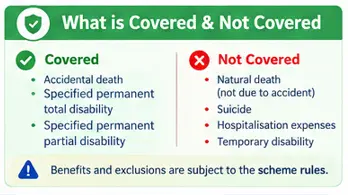
PMSBY is accident insurance, not general life insurance. The benefit depends on the outcome of a covered accident.
| Event covered under the scheme | Benefit |
|---|---|
| Accidental death | ₹2 lakh |
| Specified permanent total disability, such as qualifying loss involving both eyes or both hands or feet | ₹2 lakh |
| Specified permanent partial disability, such as qualifying loss of sight in one eye or use of one hand or foot | ₹1 lakh |
The disability definitions in the official scheme rules determine whether a benefit is payable. Not every injury, illness or temporary disability qualifies.
PMSBY does not reimburse hospitalisation expenses. If you need medical expense coverage, you will need to consider suitable health or accident insurance separately.
Read the complete PMSBY Guide 2026 for details of benefits, premiums, enrolment and claims.
7. What is not covered by PMSBY?
PMSBY provides benefits for qualifying accidental death and specified permanent disabilities. It does not pay for every death or injury.
Important points include:
- Natural death unrelated to an accident: This is not covered under PMSBY.
- Suicide: Death by suicide is not covered.
- Temporary injuries: Temporary disability or an injury that does not meet the specified disability definitions does not qualify for the disability benefit.
- Hospital bills: Hospitalisation and treatment expenses are not reimbursed by this scheme.
- Unconfirmed accidental death: A claim requires documentary evidence establishing the accident and the relevant death or disability.
The official scheme FAQ states that qualifying deaths or disabilities resulting from natural calamities, such as floods and earthquakes, may be covered because they can be treated as accidents under the scheme. The circumstances and evidence still matter.
For a claim, follow the prescribed documentation and reporting requirements. Some accidents, including road or rail incidents and cases involving a crime, may need to be reported to the police.
8. How can you check your PMSBY eligibility before applying?
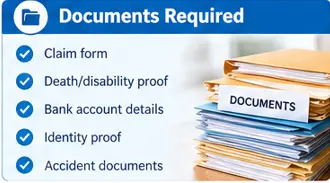
Use this simple checklist before visiting your bank or applying through its available digital service.
Step 1: Check your age. Confirm that you meet the 18–70 age rule.
Step 2: Check your account. Make sure you have an eligible individual account with a participating bank or post office.
Step 3: Check for existing enrolment. If you have more than one bank account, find out whether you already have PMSBY cover through another account.
Step 4: Confirm the premium. The current annual premium is ₹20 per person. Ask your institution to confirm the amount at the time of enrolment.
Step 5: Give consent. Complete the prescribed enrolment and auto-debit authorisation process.
Step 6: Keep the confirmation. Save the acknowledgement, SMS or other confirmation available from your bank or post office. Check that your enrolment and premium deduction are recorded.
You can obtain official scheme forms and related documents from the PMSBY forms page.
For a full walkthrough, read our guide on how to apply for PMSBY.
Final takeaway
PMSBY eligibility is straightforward: you generally need to be aged 18–70, hold an eligible account with a participating bank or post office, and consent to the annual premium deduction. At ₹20 per year, the scheme offers a basic layer of accident protection, with benefits of up to ₹2 lakh for accidental death or specified permanent total disability and ₹1 lakh for specified permanent partial disability.
Before relying on the cover, confirm that you are enrolled, that the premium has been deducted and that you understand what the policy does—and does not—cover.
Frequently asked questions about PMSBY eligibility
Q1. Can a 17-year-old join PMSBY?
No. The minimum entry age is 18 years. A person must meet the age and other eligibility conditions to enrol.
Q2. Can a 65-year-old join PMSBY?
A person aged 65 may be eligible if they meet the other conditions and have not reached the scheme’s maximum age under its rules. They should confirm enrolment with their participating bank or post office.
Q3. Is PMSBY available without a bank account?
No. The scheme requires an eligible bank or post office account through which the premium can be deducted with the member’s consent.
Q4. Can husband and wife both join PMSBY?
Yes. Both may enrol if each meets the eligibility conditions. They must have their enrolments recorded and pay the premium for each member.
Q5. Can I claim ₹2 lakh from two banks if I enrolled twice?
No. PMSBY does not provide separate benefits through multiple accounts held by the same person. Cover is restricted under the scheme rules.
Q6. Does PMSBY cover natural death?
No. PMSBY is an accident insurance scheme. Natural death unrelated to an accident is not covered. Qualifying accidental deaths, including certain accidents arising from natural calamities, may be covered subject to the rules and evidence.
Q7. Can I join PMSBY if I already have life insurance?
Yes. PMSBY may be held in addition to other insurance, subject to its eligibility and enrolment conditions. However, PMSBY specifically covers qualifying accidental death and specified permanent disabilities; it does not replace comprehensive life or health insurance.
Q8. When does PMSBY cover start?
For new enrolment, the official rules state that risk cover starts from the date the premium is auto-debited. Keep confirmation of the enrolment and deduction, and check your bank’s records if you are unsure.
Q9. Where can I read the official PMSBY rules?
Visit the Department of Financial Services PMSBY page or the official PMSBY forms and documents page.
Related Posts
- PMSBY Guide (2026): ₹2 Lakh Accident Cover, Eligibility, Premium & Claim Process
- PMSBY Premium 2026: ₹20 Annual Premium and Auto-Debit Rules
- How to Apply for PMSBY Online in 2026: Step-by-Step Guide
- PMSBY Claim Process 2026: Documents Required and How to Claim
- PMSBY Claim Rejected or Delayed? Reasons and What to Do
- PMSBY Benefits 2026: Accidental Death, Disability Cover and Exclusions
Official sources
- Department of Financial Services: PMSBY
- Jan Suraksha: PMSBY forms and documents
- India Post: PMSBY information
Benefitomics provides general information to help readers understand government schemes. Eligibility and claim decisions depend on the official scheme rules and the facts of each case. Check the latest terms with the participating bank, post office or insurer before making a decision.