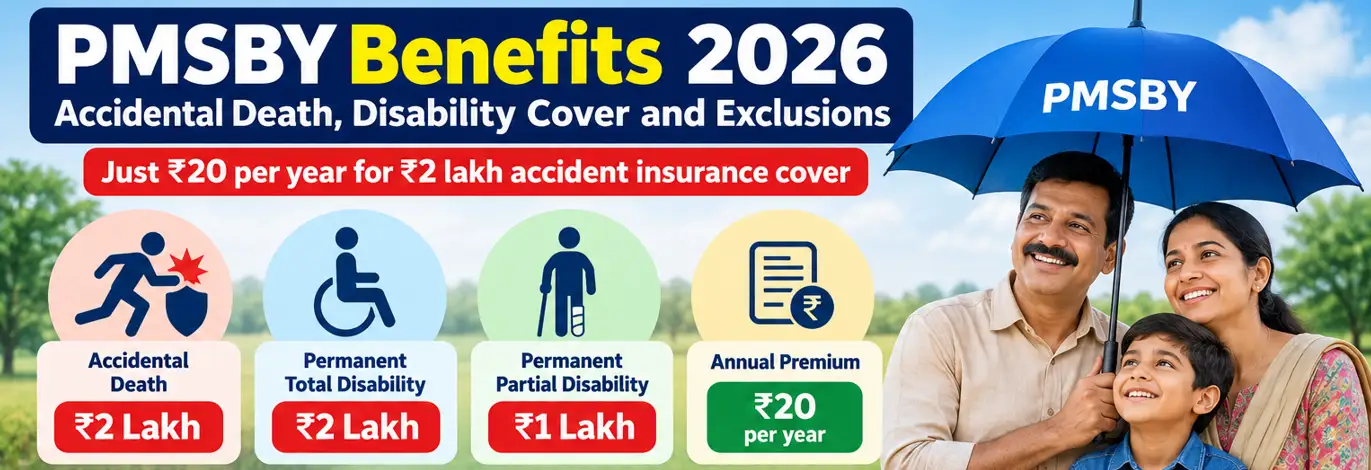
PMSBY Benefits 2026 include accidental death cover of ₹2 lakh, specified permanent total disability cover of ₹2 lakh, and specified permanent partial disability cover of ₹1 lakh under the Pradhan Mantri Suraksha Bima Yojana (PMSBY). For an annual premium of just ₹20, eligible account holders aged 18–70 can access this government-backed accident insurance scheme, subject to its terms and conditions.
Understanding PMSBY benefits, exclusions, eligibility and claim rules can help you know what the scheme covers, what it does not cover, and how to claim the applicable benefit.
The benefit is not payable for every death or injury. The accident and any resulting disability must meet the scheme’s definitions, and the claimant must provide the required evidence.
This guide explains the benefits available under PMSBY, which disabilities qualify, what is not covered and how the scheme differs from general life or health insurance.
What are the benefits of PMSBY in 2026?
The scheme’s benefit amounts are:
| Event | Benefit |
|---|---|
| Death due to a qualifying accident | ₹2 lakh |
| Specified permanent total disability | ₹2 lakh |
| Specified permanent partial disability | ₹1 lakh |
These amounts are subject to the official scheme terms and the assessment of the claim. The scheme does not provide separate claim payments through multiple bank accounts held by the same member.
You can confirm the latest benefit details on the Department of Financial Services PMSBY page.
1. PMSBY accidental death benefit: ₹2 lakh
If an enrolled member dies because of a qualifying accident, the scheme provides a benefit of ₹2 lakh, subject to its conditions and the required evidence.
The nominee recorded in the enrolment details generally submits the claim. If there is no nomination or the nominee died before the insured member, an eligible legal heir may be able to claim with the prescribed legal documents.
A death that is not caused by an accident does not qualify for the PMSBY accidental death benefit. The claimant must provide accepted documentation to establish the circumstances and cause of death.
For example, if a member dies in a qualifying road accident, the claimant should contact the bank or post office where the member enrolled and ask for the required claim form and document checklist.
2. PMSBY permanent total disability benefit: ₹2 lakh
PMSBY provides ₹2 lakh for specified permanent total disabilities resulting from a qualifying accident.
The scheme includes qualifying cases such as:
- Total and irrecoverable loss of both eyes.
- Loss of use of both hands or both feet.
- Loss of sight in one eye together with loss of use of one hand or foot.
These are specific definitions, not a general promise to pay for every serious injury. The required disability evidence must support the claim under the scheme rules.
The official claim instructions may require an FIR or panchnama, a disability certificate from the Civil Surgeon and supporting hospital records. Ask the claim-handling institution which documents are required for your case.
3. PMSBY permanent partial disability benefit: ₹1 lakh
PMSBY provides ₹1 lakh for specified permanent partial disabilities, including:
- Total and irrecoverable loss of sight in one eye.
- Loss of use of one hand or one foot, as defined by the scheme.
The term “partial disability” can be misunderstood. PMSBY does not pay the benefit for every injury described as a partial disability by a doctor or claimant. The condition must match the specified loss under the scheme.
The official scheme FAQ states that no benefit is payable for a partial disability that does not meet the specified permanent loss definitions.
4. What is covered under PMSBY?
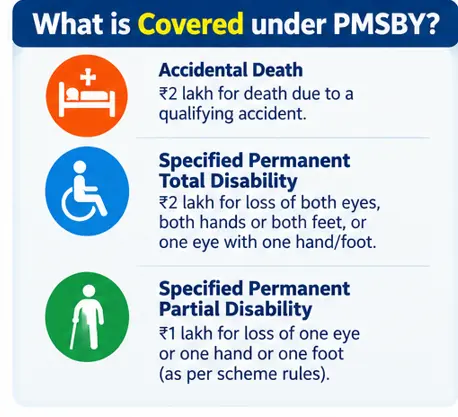
PMSBY covers qualifying accidental death and specified permanent disabilities. The official definition describes an accident as a sudden, unforeseen and involuntary event caused by external, violent and visible means.
The scheme FAQ also states that deaths or disabilities arising from natural calamities such as floods and earthquakes may be covered when they meet the scheme’s definition of an accident.
However, the circumstances and supporting evidence matter. If you are unsure whether an incident qualifies, ask the insurer or participating bank to explain the applicable rule.
5. What is not covered by PMSBY?
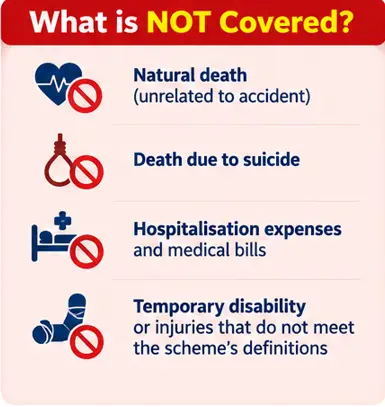
Understanding the limitations is just as important as knowing the benefits.
Natural death unrelated to an accident: PMSBY is personal accident insurance, so ordinary natural death is not covered.
Death by suicide: The official scheme FAQ states that death due to suicide is not covered.
Temporary disability: A temporary injury or disability that does not meet the scheme’s specified permanent disability definitions does not qualify for the disability benefit.
Hospitalisation expenses: PMSBY does not reimburse hospital bills, medicines, surgery or other treatment costs.
Unconfirmed accidental death: The claim must be supported by documentary evidence establishing the accidental death. A missing person whose death has not been confirmed does not automatically qualify for the death benefit.
Unspecified disability: Not every loss of income, injury or impairment qualifies. The permanent loss must meet the scheme’s definitions.
These exclusions and conditions are important when deciding whether PMSBY provides the protection you need.
6. Who can receive the PMSBY benefit?
The person who receives the benefit depends on the type of claim.
- Death claim: The benefit is generally paid to the recorded nominee or eligible legal heir.
- Minor nominee: The appointed person recorded for the minor nominee may act as required by the scheme.
- Disability claim: The benefit is generally paid into the insured member’s bank account.
If the nominee has died before the insured member, or no nomination was recorded, the legal heir may need to provide the applicable succession certificate or legal-heir certificate from a competent court or authority.
Check the enrolment record and the official claim form before submitting the application.
7. What does PMSBY cost?
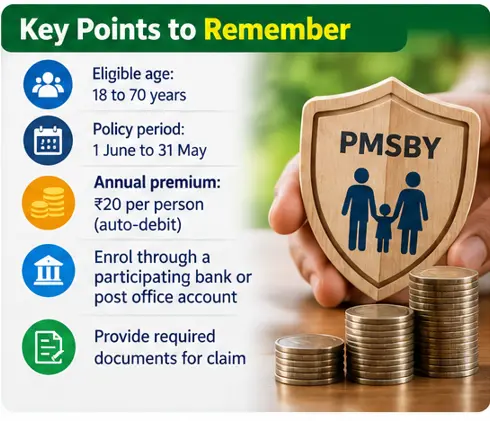
The current annual premium is ₹20 per member, collected through auto-debit from an eligible bank or post office account with the subscriber’s consent.
The cover period runs from 1 June to 31 May. Eligible new entrants or people rejoining later may enrol subject to the scheme rules, with cover beginning from the date of premium auto-debit.
To maintain cover, keep your account active and ensure the premium deduction succeeds. If a deduction fails, contact the participating institution to confirm your status.
Read our guide to PMSBY Premium 2026 for more details about auto-debit and renewal.
8. PMSBY versus life and health insurance
PMSBY offers affordable accident protection, but it is not a complete replacement for other insurance.
| Feature | PMSBY | Life insurance | Health insurance |
|---|---|---|---|
| Main purpose | Qualifying accidental death and specified permanent disability | Financial protection for death under policy terms | Medical expenses under policy terms |
| Current PMSBY premium | ₹20 per year | Depends on policy | Depends on policy |
| Hospital bills | Not reimbursed | Generally not a medical-expense benefit | May be covered under policy terms |
| Natural death | Not covered by PMSBY | May be covered under a suitable life policy | Not a death benefit |
| Permanent disability | Only specified qualifying losses | Depends on policy and riders | Depends on policy and benefits |
A person can hold PMSBY alongside other insurance, subject to the relevant terms. The official scheme FAQ confirms that PMSBY cover can be in addition to other insurance.
If you want to understand the difference between the two government insurance schemes, read our PMJJBY vs PMSBY comparison.
9. How to claim PMSBY benefits
If an insured member suffers a qualifying accident, contact the bank or post office through which they enrolled.
The general process is:
- Inform the participating institution.
- Obtain the official PMSBY claim form.
- Collect the relevant death or disability evidence.
- Provide claimant identity and bank account details.
- Submit the completed form and supporting documents.
- Keep an acknowledgement and follow up using the claim reference.
The official claim form says the claim should preferably be submitted within 30 days of the accident. If that period has passed, contact the bank or insurer promptly to ask how to proceed.
See our detailed guide to the PMSBY Claim Process 2026 for the documents and steps.
Final takeaway
PMSBY offers a basic layer of accident protection for an annual premium of ₹20. The scheme provides ₹2 lakh for qualifying accidental death or specified permanent total disability and ₹1 lakh for specified permanent partial disability.
Before relying on it, understand the exclusions, confirm that your enrolment is active and keep the official scheme information available. If an accident occurs, contact the participating bank or post office promptly and follow the prescribed claim process.
Frequently asked questions about PMSBY benefits
Q1. How much does PMSBY pay for accidental death?
The benefit is ₹2 lakh for a qualifying accidental death, subject to the scheme’s terms and documentary evidence.
Q2. Does PMSBY pay ₹2 lakh for every disability?
No. The ₹2 lakh benefit applies to specified permanent total disabilities. The scheme provides ₹1 lakh for specified permanent partial disabilities. Other injuries may not qualify.
Q3. Does PMSBY cover hospital bills?
No. The scheme does not reimburse hospitalisation expenses following an accident.
Q4. Are natural calamities covered by PMSBY?
Qualifying death or disability arising from natural calamities such as floods or earthquakes may be covered when the event meets the scheme rules and is supported by the required evidence.
Q5. Does PMSBY cover natural death?
No. Death unrelated to an accident is not covered by PMSBY.
Q6. Can I receive PMSBY benefits if I already have other insurance?
Yes. PMSBY may be held in addition to other insurance, subject to each policy’s terms. The scheme does not replace life or health insurance.
Q7. What is the premium for PMSBY in 2026?
The current annual premium is ₹20 per enrolled member, paid through auto-debit from an eligible account with consent.
Q8. Where can I read the official PMSBY rules?
Visit the Department of Financial Services PMSBY page and the official PMSBY forms page.
Related Posts
- PMSBY Guide (2026): ₹2 Lakh Accident Cover, Eligibility, Premium & Claim Process
- PMSBY Eligibility 2026: Who Can Get ₹2 Lakh Accident Cover?
- PMSBY Premium 2026: ₹20 Annual Premium and Auto-Debit Rules
- How to Apply for PMSBY Online in 2026: Step-by-Step Guide
- PMSBY Claim Process 2026: Documents Required and How to Claim
- PMSBY Claim Rejected or Delayed? Reasons and What to Do
Official sources
Benefitomics is an independent information website, not an official government portal. Coverage and claim decisions are subject to the official scheme terms and the evidence provided.