If your PMSBY claim is rejected or delayed, first ask the bank or insurer for the specific reason. The problem may involve missing documents, unclear accident evidence, nominee details, an inactive policy or a question about whether the event qualifies under the scheme. The next step is to check the claim record and respond to the issue identified.
The Pradhan Mantri Suraksha Bima Yojana (PMSBY) provides benefits for qualifying accidental death and specified permanent disabilities. A claim is assessed under the scheme rules, so not every accident, injury or death automatically qualifies.
This guide explains common PMSBY claim problems, what to check, how to follow up and where to raise a complaint if the matter remains unresolved.
Why is a PMSBY claim rejected or delayed?
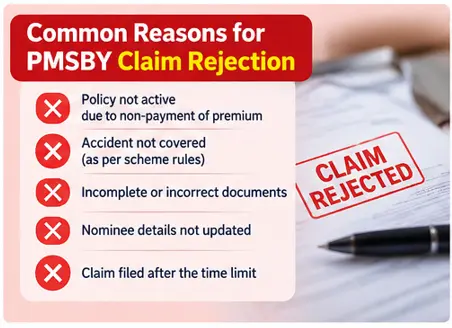
A claim may require additional checking if the insurer or bank cannot verify the cover, the event or the supporting documents. Common issues include:
- Missing or incomplete claim documents.
- Unclear proof of accidental death or specified permanent disability.
- Differences in the insured member’s name, account details or other records.
- Missing nominee or legal-heir documentation.
- Questions about whether the insurance cover was active on the date of the accident.
- An event or injury that does not meet the scheme’s benefit definitions.
- Delays in transferring documents between the bank, post office and insurer.
These are possible reasons to investigate, not a statement that your claim has been rejected for any particular reason. Ask for the actual reason before deciding what to do next.
1. Ask for the reason in writing
If you have received a rejection message or your claim has remained pending, contact the bank or post office where the claim was submitted.
Provide your claim acknowledgement or reference number and ask:
- Has the claim been forwarded to the insurer?
- Is any document missing?
- Has the insurer requested clarification?
- Has a decision been made?
- If the claim was rejected, what specific reason was recorded?
Request a written explanation or a copy of the decision if available. It is much easier to address a clearly stated issue than to guess why the claim is stuck.
2. Check whether the PMSBY cover was active
PMSBY has an annual cover period from 1 June to 31 May, subject to the scheme’s conditions. The annual premium is currently ₹20 and is collected through auto-debit with the subscriber’s consent.
Check the bank account statement and enrolment record to confirm:
- The premium was deducted.
- The relevant enrolment was recorded.
- The accident happened during the applicable cover period.
- The account and policy details match the claim records.
If the premium was not deducted, ask the bank or insurer to explain the effect on your coverage. Do not assume that an application or an earlier year’s deduction proves that the cover was active on the date of the accident.
3. Check whether the required documents were submitted
Missing evidence can delay a claim. Review the documents requested for your particular case.
For an accidental death claim, the insurer may need the prescribed claim form and accepted evidence of death and the accident. Depending on the circumstances, this may include a death certificate, hospital records, FIR or panchnama, and a post-mortem report.
For a permanent disability claim, the prescribed evidence may include a disability certificate from the Civil Surgeon, hospital records and relevant police documents.
The nominee or claimant may also need identity documents, bank account details and nominee or legal-heir evidence where applicable.
Use the official PMSBY claim form to review the document instructions. If anything is missing, ask the claim-handling office how to submit it and obtain an acknowledgement.
4. What if the nominee details are incorrect or there is no nominee?
A difference between the enrolment record and the claimant’s details may require clarification.
Ask the bank to check the nomination recorded for the policy. If the nominee has died before the insured member, or no nomination was made, an eligible legal heir may be able to claim subject to the prescribed legal documentation.
The official PMSBY claim form explains that a legal heir in these circumstances may need a succession certificate or legal-heir certificate issued by a competent court or authority.
Do not assume that a family relationship alone will be enough to complete the claim. Ask the bank or insurer what documentation applies to your case.
5. What if the accident or disability does not appear to qualify?
PMSBY is accident insurance, not general life insurance or health insurance.
The scheme’s specified benefits include:
- ₹2 lakh for accidental death.
- ₹2 lakh for specified permanent total disability.
- ₹1 lakh for specified permanent partial disability.
Not every injury or disability qualifies. For example, PMSBY does not cover temporary disability or hospitalisation expenses. Natural death unrelated to an accident is also not covered. Qualifying deaths or disabilities arising from certain natural calamities may be covered under the scheme rules.
If the insurer says the event does not qualify, ask which policy definition or condition was applied. Compare that explanation with the official scheme terms and the evidence submitted.
6. Follow up if the claim is pending
If you have not received an update, use a documented follow-up process:
- Contact the bank or post office that received the claim.
- Provide the acknowledgement or reference number.
- Ask whether the claim has been sent to the insurer.
- Confirm whether the insurer needs additional documents or clarification.
- Contact the insurer’s designated claim or grievance team if the matter remains unresolved.
- Keep copies of emails, letters, acknowledgement receipts and responses.
Be clear and factual in your communication. Include the insured member’s details as requested by the institution, the claim reference, the submission date and the specific help you need. Do not share sensitive account details publicly on social media.
7. How to raise a complaint about a PMSBY claim
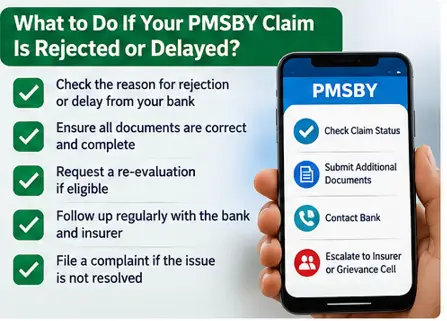
If repeated follow-ups do not resolve the issue, use the formal grievance process.
First, complain to the insurer. Ask for the insurer’s grievance redressal channel and submit a written complaint with the claim reference and relevant records. Keep the complaint acknowledgement.
Next, escalate if necessary. If the insurer does not resolve the complaint or you are dissatisfied with the response, you can consider the applicable insurance grievance channels, including the IRDAI’s Bima Bharosa portal.
You can also review the Council for Insurance Ombudsmen website to understand whether your dispute is eligible for Ombudsman consideration and what conditions apply.
Use official websites and contact details. Do not pay anyone who promises to release your claim, and do not scan a QR code or share an OTP to receive insurance money.
8. How to write a follow-up message to the bank or insurer
You can adapt this short message for an email or written complaint.
Subject: Request for update on PMSBY claim
Dear Sir/Madam,
I am writing to request an update on a claim submitted under the Pradhan Mantri Suraksha Bima Yojana (PMSBY).
Claim reference: [Enter reference number]
Date of submission: [Enter date]
Type of claim: [Accidental death / permanent disability]
Please confirm the current status of the claim and let me know whether any additional documents or clarification are required. If a decision has already been made, kindly provide the reason in writing and explain the next steps available to me.
Thank you.
Yours faithfully,
[Name of claimant]
Use this as a template and fill in only the information requested by the institution. Do not include passwords, PINs or OTPs.
Final takeaway
A rejected or delayed PMSBY claim needs a clear explanation and a documented response. Check whether the cover was active, ask for the exact reason, review the required evidence and follow up with the bank or insurer. If the problem remains unresolved, use the formal grievance process.
Keep every acknowledgement and written response. It will help you explain the issue clearly if you need to escalate the complaint.
Frequently asked questions
Q1. What should I do first if my PMSBY claim is rejected?
Ask the bank or insurer for the specific reason in writing. Check the cover record, the claim form and the supporting documents before responding.
Q2. Can I submit missing documents after filing a PMSBY claim?
Ask the claim-handling bank or insurer whether the documents can be added and how to submit them. Keep proof of submission and follow any instructions or deadlines provided.
Q3. Can I complain if my PMSBY claim is delayed?
Yes. Start with the bank or post office handling the claim and the insurer’s grievance process. If the matter remains unresolved, review the available insurance grievance channels, including IRDAI Bima Bharosa and, where eligible, the Insurance Ombudsman.
Q4. Will every accident qualify for PMSBY benefits?
No. The event must meet the scheme’s conditions, and the disability benefit applies only to specified permanent losses. Temporary disability and hospitalisation expenses are not covered benefits under PMSBY.
Q5. What if there is no nominee?
An eligible legal heir may be able to claim. The official claim form specifies the legal documentation that may be required if there is no nomination or if the nominee died before the insured member.
Q6. How can I download the official PMSBY claim form?
Use the official PMSBY forms page or download the PMSBY claim form PDF.
Related Posts
- PMSBY Guide (2026): ₹2 Lakh Accident Cover, Eligibility, Premium & Claim Process
- PMSBY Eligibility 2026: Who Can Get ₹2 Lakh Accident Cover?
- PMSBY Premium 2026: ₹20 Annual Premium and Auto-Debit Rules
- How to Apply for PMSBY Online in 2026: Step-by-Step Guide
- PMSBY Claim Process 2026: Documents Required and How to Claim
- PMSBY Benefits 2026: Accidental Death, Disability Cover and Exclusions
Official sources
- Department of Financial Services: PMSBY
- Jan Suraksha: PMSBY forms
- IRDAI Bima Bharosa
- Council for Insurance Ombudsmen
Benefitomics is an independent information website and does not decide insurance claims. The insurer’s decision depends on the scheme terms, the evidence and the circumstances of the claim.