
An accident can affect a family’s finances in ways that are difficult to plan for. Even when medical treatment is available, the loss of an earning family member or a permanent disability can create long-term financial pressure.
The Pradhan Mantri Suraksha Bima Yojana (PMSBY) is a government-backed personal accident insurance scheme designed to provide basic financial protection at a low annual premium.
PMSBY offers eligible subscribers ₹2 lakh for accidental death or specified permanent total disability and ₹1 lakh for specified permanent partial disability. The published annual premium is ₹20, and the entry age is 18–70 years. The benefit depends on the type of accident, the resulting loss and the scheme’s conditions.
This PMSBY Guide 2026 explains who can join, what the scheme covers, how to enrol, which documents may be needed and how to submit a claim.
What Is PMSBY?

PMSBY stands for Pradhan Mantri Suraksha Bima Yojana. It is a renewable, one-year personal accident insurance scheme offered through participating banks and eligible post office accounts in association with authorised general insurance companies.
The scheme is intended to provide financial support when a qualifying accident causes death or certain specified permanent disabilities.
Unlike life insurance that generally covers death due to different causes, PMSBY focuses on accidental death and specified permanent disability. It does not provide general life insurance for natural death or illness.
PMSBY Guide 2026: Eligibility, Benefits and Claim Process
PMSBY scheme details at a glance

| Feature | Details |
|---|---|
| Full name | Pradhan Mantri Suraksha Bima Yojana |
| Type of cover | Personal accident insurance |
| Annual premium | ₹20 per person at the published rate |
| Entry age | 18–70 years |
| Accidental death benefit | ₹2 lakh |
| Specified permanent total disability benefit | ₹2 lakh |
| Specified permanent partial disability benefit | ₹1 lakh |
| Cover period | 1 June to 31 May |
| Premium payment | Annual auto-debit from the designated eligible account |
| Enrolment | Through a participating bank or eligible post office |
| Renewal | Annual, subject to scheme conditions |
These details follow the Government of India’s Department of Financial Services information. Check the official PMSBY scheme page for any subsequent changes.
What Are the Benefits of PMSBY?
The amount payable depends on the outcome of the accident. Not every accident or injury qualifies for an insurance payment.
1. ₹2 lakh for eligible accidental death
If an insured subscriber dies due to a covered accident, the nominee or other eligible claimant may receive ₹2 lakh, subject to the policy terms and supporting documents.
The death must be established through acceptable evidence. A missing person cannot automatically be treated as a confirmed accidental death for claim purposes.
2. ₹2 lakh for specified permanent total disability
The scheme provides ₹2 lakh for specified permanent and irrecoverable losses, including qualifying loss of both eyes, loss of use of both hands or feet, or the specified combination of loss of sight in one eye and loss of use of a hand or foot.
The exact definition and documentary requirements in the scheme apply.
3. ₹1 lakh for specified permanent partial disability
The scheme provides ₹1 lakh for specified permanent and irrecoverable loss of sight in one eye or loss of use of one hand or foot.
A temporary injury, fracture or period of hospitalisation does not automatically qualify for this benefit. The disability must meet the scheme’s specified conditions.
PMSBY benefit table
| Accident outcome | Published benefit |
|---|---|
| Eligible accidental death | ₹2 lakh |
| Specified permanent total disability | ₹2 lakh |
| Specified permanent partial disability | ₹1 lakh |
| Temporary injury or hospitalisation alone | No automatic benefit |
Who Is Eligible for PMSBY in 2026?
This PMSBY Guide 2026 explains who can enrol in the scheme, how the ₹20 annual premium works, which accidental death and disability benefits are available, and how eligible families can submit a claim.

PMSBY is available to eligible individual account holders aged 18–70 years who meet the scheme requirements.
You generally need to:
- Be at least 18 and not have crossed the applicable upper entry-age limit of 70.
- Hold an eligible individual bank or post office account with a participating institution.
- Give consent to join the scheme.
- Authorise the annual premium auto-debit.
- Meet the applicable enrolment and policy conditions.
Both single and joint account holders can join if they individually satisfy the eligibility requirements. Each eligible person must enrol and pay the applicable premium.
Can you join PMSBY if you have multiple bank accounts?
An individual can enrol through only one eligible bank or post office account for PMSBY coverage.
If the same person is enrolled through more than one account and premiums are collected inadvertently, the cover is restricted to one account under the scheme rules. Do not expect duplicate enrolments to provide multiple benefits.
Can NRIs join PMSBY?
The official scheme information allows an NRI with an eligible bank account at a bank branch in India to purchase PMSBY cover, subject to the scheme’s conditions. If a claim is approved, the benefit is payable in Indian currency.
For individual eligibility, confirm the current rules with the participating institution.
What Is the PMSBY Premium in 2026?
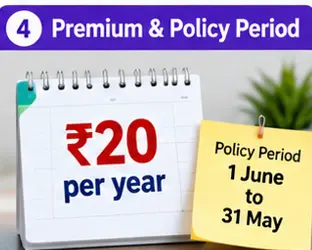
The published annual premium is ₹20 per person.
The amount is collected through an authorised auto-debit from the designated bank or eligible post office account. The premium is for one year’s cover and is not a monthly payment.
For example, if two eligible adults in a family enrol separately, their combined annual premium at the published rate would be ₹40.
The premium is low, but enrolment and active coverage still matter. Do not assume that having an account or having enrolled in a previous year means your cover is active today.
What happens if your account has insufficient balance?
The bank or post office needs to collect the applicable premium to maintain coverage under the scheme rules. Insufficient balance, account closure or other qualifying circumstances can cause cover to terminate or be restricted.
Keep the designated account active and adequately funded around the premium collection date. If you are unsure whether the premium was deducted, ask your bank to confirm your enrolment and coverage status.
Can you join PMSBY after the initial enrolment period?
Eligible people can join in subsequent years by paying the applicable premium through auto-debit. The official scheme information states that risk cover starts from the date the premium is auto-debited from the subscriber’s account.
If you leave the scheme and later rejoin, the applicable rules and cover-start date should be checked with the participating institution.
What Is the PMSBY Policy Period?
PMSBY generally provides one year of cover from 1 June to 31 May and is renewable annually.
At enrolment, the subscriber authorises the participating institution to collect the premium for renewal, subject to the scheme’s conditions.
To avoid an unintended gap in protection:
- Keep the designated account open and active.
- Maintain sufficient balance for the premium.
- Check the premium debit entry.
- Ask the bank or post office to confirm your current coverage if you have any doubt.
The scheme’s accident cover terminates on reaching age 70, and other conditions such as account closure or insufficient balance can also affect coverage.
What Does PMSBY Cover—and What Does It Not Cover?
Understanding the limits is as important as knowing the benefit amount.
What PMSBY covers
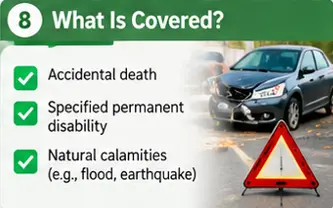
PMSBY covers eligible accidental death and the specified permanent disabilities listed in the scheme.
The official definition describes an accident as a sudden, unforeseen and involuntary event caused by external, violent and visible means.
The official FAQ also states that qualifying death or disability resulting from natural calamities, such as floods or earthquakes, may be covered because these events are treated as accidents under the scheme. Coverage depends on the circumstances and the policy definition.
What PMSBY does not cover
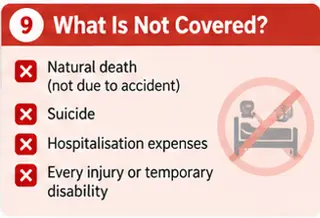
PMSBY is not a substitute for every kind of insurance.
- Natural death unrelated to an accident: Not covered.
- Death due to suicide: Not covered under the scheme.
- Hospitalisation expenses: Not reimbursed simply because an accident occurred.
- Every injury or temporary disability: Not automatically covered.
- Unspecified partial disability: No benefit is payable unless the loss meets the scheme’s defined conditions.
If an accident leads to hospitalisation but not a qualifying death or specified permanent disability, PMSBY does not automatically pay the hospital bill.
For more complete protection, consider your family’s needs for health insurance, life insurance and emergency savings separately.
How to Apply for PMSBY Online or Through Your Bank
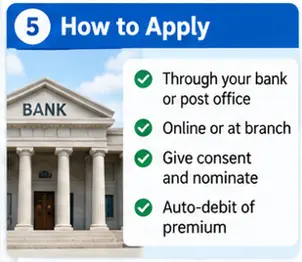
PMSBY enrolment is available through participating banks and eligible post offices. Some institutions offer digital enrolment through their official mobile banking or internet banking services. The exact steps differ by institution.
Step 1: Check your eligibility
Confirm that you meet the age and account requirements.
Step 2: Contact your bank or post office
Ask whether the institution participates in PMSBY and which enrolment options are available.
Step 3: Complete the enrolment process
Use the prescribed application or consent form, or the institution’s official digital process where available.
Step 4: Provide the required details
Check your personal details and nominee information carefully. Authorise the premium auto-debit from the eligible designated account.
Step 5: Confirm the premium deduction
Check your account statement or ask the institution for confirmation. Keep any acknowledgement or enrolment record.
Step 6: Check that your cover is active
Do not assume that the application alone guarantees coverage. Confirm the premium debit and cover-start date with the participating institution.
You can find the official application forms on the Government of India’s PMSBY forms page.
PMSBY Claim Process: How to Claim ₹2 Lakh
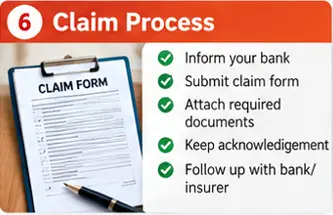
A claim may be made after an insured subscriber’s eligible accidental death or specified permanent disability. The procedure differs depending on whether the claim is for death or disability.
The official claim form says it should preferably be submitted within 30 days of the accident that gives rise to the claim. Contact the bank or post office promptly, even if that period has already passed, and ask how to proceed.
Step 1: Inform the bank or post office
Notify the participating institution where the subscriber was enrolled. Ask for the PMSBY claim form and the current document checklist.
Step 2: Obtain the official claim form
Download the form from the official PMSBY forms page or request it from the institution.
The official PMSBY Claim-cum-Discharge Form includes details about the subscriber, the accident, the nominee or claimant and the required supporting evidence.
Step 3: Complete the claim form
Provide accurate details, including the subscriber’s account information, date and nature of the accident, and details of the death or disability.
For a death claim, the nominee or other eligible claimant completes the relevant sections. For a disability claim, the insured subscriber completes the relevant sections.
Step 4: Attach the required documents
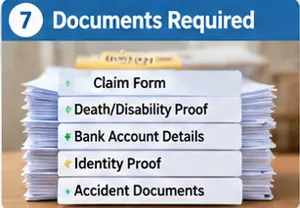
Depending on the circumstances, documents may include:
- Completed PMSBY Claim-cum-Discharge Form.
- Proof of death due to the accident or proof of the specified permanent disability.
- Claimant’s KYC document.
- Bank account details of the nominee, appointee, legal heir or insured person, as applicable.
- Proof of relationship or legal-heir entitlement where required.
- Police records or other accident-related documents where applicable.
The official form marks Aadhaar and PAN as optional. Confirm any current KYC requirements with the institution rather than assuming these are compulsory in every claim.
Step 5: Submit the claim and keep acknowledgement
Submit the form and supporting documents through the prescribed channel. Keep a copy and ask for an acknowledgement or reference number.
Step 6: Follow up
Ask whether the claim has been forwarded to the insurer and whether any additional documents are required. Keep records of communication and the submission date.
The final decision depends on the scheme conditions, the accident evidence and the documents provided.
Which Documents May Be Required for a PMSBY Claim?
The requirements depend on whether the claim is for accidental death or disability.
| Document or information | Why it may be needed |
|---|---|
| PMSBY claim form | Records the claim and relevant details |
| Proof of death or specified disability | Establishes the event and qualifying outcome |
| Subscriber’s account details | Helps verify enrolment records |
| Claimant’s KYC documents | Establishes the identity of the nominee or claimant |
| Nominee or legal-heir details | Establishes who may receive the death benefit |
| Accident-related records | Supports the circumstances of the accident where required |
| Bank details of the eligible recipient | Allows the benefit to be credited if approved |
For road, rail and similar vehicular accidents, drowning or death involving a crime, the official FAQ says the incident should be reported to the police. For events such as a snakebite or a fall from a tree, immediate hospital records may be required to support the cause.
Follow the current official claim form and the institution’s instructions for the specific case.
Who Receives the PMSBY Claim Amount?
For an eligible accidental death claim, payment is generally made to the nominee or eligible legal heir, as applicable under the scheme.
If the nominee is a minor, the appointee recorded in the nomination may act on the minor’s behalf. If there is no nomination or the nominee died before the insured subscriber, eligible legal heirs may need to establish their entitlement with the required documents.
For a qualifying disability claim, the scheme credits the benefit to the insured subscriber’s bank account.
Can You Have Both PMSBY and PMJJBY?
Yes. Eligible individuals can enrol in both schemes, subject to their respective rules.
The schemes provide different types of protection:
- PMSBY: Eligible accidental death and specified permanent disability.
- PMJJBY: Life insurance for death due to any cause, subject to its terms and the applicable waiting-period rule.
At their published annual premiums, PMJJBY costs ₹436 and PMSBY costs ₹20, making the combined annual premium ₹456 for someone enrolled in both at these rates.
A qualifying accidental death may be considered under both schemes if both covers are active and each claim meets its conditions. The benefit is not automatic; each claim is assessed under the relevant scheme.
Read our comparison: PMJJBY vs PMSBY 2026: Difference Between Life and Accident Insurance.
Final Takeaway
PMSBY offers a simple form of accident protection at a published annual premium of ₹20. For eligible subscribers, the benefit can be ₹2 lakh for accidental death or specified permanent total disability and ₹1 lakh for specified permanent partial disability.
But it is important to understand the limits. PMSBY does not cover natural death unrelated to an accident, and it does not pay hospital bills simply because someone is injured.
Check your eligibility, confirm the premium deduction, keep your nominee details up to date and save the official claim form information. If an accident occurs, contact the participating bank or post office promptly and follow the claim process.
Discover. Understand. Benefit.
Frequently Asked Questions About PMSBY
1. What is PMSBY and how much insurance does it provide?
PMSBY is a government-backed personal accident insurance scheme. It provides ₹2 lakh for eligible accidental death or specified permanent total disability and ₹1 lakh for specified permanent partial disability.
2. What is the PMSBY premium in 2026?
The published annual premium is ₹20 per person. Check the official scheme page for any revised rate.
3. Who can join PMSBY?
Eligible individual bank or post office account holders aged 18–70 can join, subject to the scheme requirements and authorisation of premium auto-debit.
4. Does PMSBY cover natural death?
No. PMSBY is accident insurance. Death unrelated to an accident is not covered.
5. Does PMSBY pay hospital bills after an accident?
No. The scheme does not reimburse hospitalisation expenses merely because an accident occurred. Its benefits relate to eligible accidental death and specified permanent disability.
6. Can I join PMSBY through two bank accounts?
No. An individual can obtain PMSBY cover through only one eligible account. Multiple enrolments do not provide multiple benefits.
7. Can I apply for PMSBY after missing the initial enrolment period?
Eligible individuals can join in subsequent years by paying the applicable premium through auto-debit. The official scheme information states that risk cover starts from the date the premium is debited.
8. How soon should I submit a PMSBY claim?
The official claim form recommends submission preferably within 30 days of the accident. Inform the bank or post office promptly and ask for the procedure if that period has passed.
9. Can I claim PMSBY for a permanent disability?
A benefit may be payable if the accident results in one of the specified permanent disabilities covered by the scheme. The amount is ₹2 lakh or ₹1 lakh depending on the qualifying loss.
10. Can I join PMSBY and PMJJBY together?
Yes, eligible individuals can enrol in both. PMSBY provides accident protection, while PMJJBY provides life insurance subject to its conditions.
This guide is for general information and is not personalised insurance advice. Benefits depend on the official scheme terms, the facts of the accident and the documents provided. Verify the latest rules with the Government of India and your participating institution before enrolling or making a claim.
Official Sources
- Department of Financial Services – PMSBY
- PMSBY application and claim forms
- Official PMSBY Claim-cum-Discharge Form (PDF)
Related Posts
- PMSBY Eligibility 2026: Who Can Get ₹2 Lakh Accident Cover?
- PMSBY Premium 2026: ₹20 Annual Premium and Auto-Debit Rules
- How to Apply for PMSBY Online in 2026: Step-by-Step Guide
- PMSBY Claim Process 2026: Documents Required and How to Claim
- PMSBY Claim Rejected or Delayed? Reasons and What to Do
- PMSBY Benefits 2026: Accidental Death, Disability Cover and Exclusions